Research QuantBook: Framework Composite FamaFrench + AllWeather

Objectif

Analyser la combinaison de deux stratégies complementaires: - FamaFrench Alpha: Rotation des 5 factor ETFs (VLUE, MTUM, SIZE, QUAL, USMV) basee sur momentum risk-adjuste - AllWeather Alpha: Allocation statique macro (SPY/IEF/GLD/XLP = 30/30/30/10)

Design principle cle

Lecon apprise de MomentumRegime: PAS d’overlap entre les univers. - FamaFrench: equity factors (facteurs Fama-French) - AllWeather: traditional assets (equities, bonds, gold, staples) - Vraie diversification: facteurs de marche + allocation macro

Hypotheses a tester

  1. Allocation optimale: Ratio FF/AW (10/90, 20/80, 30/70, 40/60, 50/50)
  2. Impact du SMA200 sur FamaFrench: AVEC vs SANS filtre (AllWeather gere le defensif)
  3. Nombre de facteurs positifs: Top-2 vs Tous positifs vs USMV fallback

Performance de reference

  • FamaFrench v3.0: Sharpe 0.540, CAGR 12.1%, MaxDD 24.2%
  • AllWeather: Sharpe 0.667 (2015-2025)
  • Sweep result: FF20/AW80 → Sharpe 0.588, CAGR 9.9%, MaxDD 17.1%

Prerequis

  • Environnement Lean Research
  • Duree estimee: ~10 minutes
# Setup QuantBook
from AlgorithmImports import *
import numpy as np
import pandas as pd
import matplotlib.pyplot as plt
import warnings
warnings.filterwarnings('ignore')

plt.style.use('seaborn-v0_8-darkgrid')
plt.rcParams['figure.figsize'] = (14, 5)

qb = QuantBook()
print("QuantBook initialise.")
QuantBook initialise.

1. Chargement des données

On charge les 5 factor ETFs Fama-French et les 4 assets AllWeather.

# FamaFrench universe: 5 factor ETFs
ff_tickers = ["VLUE", "MTUM", "SIZE", "QUAL", "USMV"]

# AllWeather universe: 4 traditional assets
aw_tickers = ["SPY", "IEF", "GLD", "XLP"]

# Benchmark pour regime detection
all_tickers = ff_tickers + aw_tickers

symbols = {}
for ticker in all_tickers:
    symbols[ticker] = qb.add_equity(ticker, Resolution.DAILY).symbol

# Charger l'historique (2010-2026 pour inclure une periode complete)
start = datetime(2010, 1, 1)
end = datetime(2026, 1, 1)

history = qb.history(list(symbols.values()), start, end, Resolution.DAILY)
print(f"Donnees chargees: {len(history)} lignes")
Donnees chargees: 4024 lignes

Pivot de la série ‘close’ en DataFrame large, avec remapping des colonnes Symbol → ticker pour Framework_Composite_FamaFrenchAllWeather.

# Pivoter les donnees
closes = history['close'].unstack(level=0)

symbol_to_ticker = {str(v): k for k, v in symbols.items()}
closes.columns = [symbol_to_ticker.get(str(c), str(c)) for c in closes.columns]
closes = closes.dropna()

print(f"Periode: {closes.index[0].date()} a {closes.index[-1].date()}")
print(f"Donnees: {len(closes)} jours de trading")
print(f"Tickers: {list(closes.columns)}")
Periode: 2010-01-04 a 2025-12-31
Donnees: 4024 jours de trading
Tickers: ['SPY']

2. Implementation des signaux Alpha

def compute_risk_adjusted_momentum(closes, tickers, lookback=252, skip_days=21, vol_window=63):
    """Calcule le momentum risk-adjuste pour les factor ETFs."""
    scores = pd.DataFrame(index=closes.index, columns=tickers)
    
    for ticker in tickers:
        if ticker not in closes.columns:
            continue
        
        prices = closes[ticker]
        scores[ticker] = np.nan
        
        for i in range(lookback, len(prices)):
            # Momentum 12m-1m (skip dernier mois)
            past_price = prices.iloc[i - lookback]
            skip_idx = max(i - skip_days, lookback)
            skip_price = prices.iloc[skip_idx]
            
            if past_price <= 0:
                continue
            
            momentum_return = (skip_price / past_price) - 1
            
            # Volatilite realisee 63j
            recent_prices = prices.iloc[max(0, i - vol_window):i]
            if len(recent_prices) < 20:
                continue
            
            daily_rets = recent_prices.pct_change().dropna()
            realized_vol = daily_rets.std() * np.sqrt(252)
            
            if realized_vol <= 0.001:
                continue
            
            scores[ticker].iloc[i] = momentum_return / realized_vol
    
    return scores

def compute_famafrench_signals(closes, tickers, scores_df, use_sma200=False):
    """Genere les signaux FamaFrench (mensuels)."""
    signals = pd.DataFrame(index=closes.index, columns=tickers)
    
    sma200 = closes['SPY'].rolling(200).mean() if 'SPY' in closes.columns else None
    
    for i in range(252, len(closes)):
        # Filtre SMA200 (optionnel)
        if use_sma200 and sma200 is not None:
            spy_price = closes['SPY'].iloc[i]
            spy_sma = sma200.iloc[i]
            if pd.notna(spy_sma) and spy_price <= spy_sma:
                # Risk-off: USMV seulement
                for t in tickers:
                    signals[t].iloc[i] = 1 if t == "USMV" else 0
                continue
        
        # Calculer les scores actuels
        current_scores = {}
        for t in tickers:
            if t in scores_df.columns:
                score = scores_df[t].iloc[i]
                if pd.notna(score):
                    current_scores[t] = score
        
        if len(current_scores) < 2:
            continue
        
        # Selectionner tous les facteurs avec momentum positif
        positive_factors = [t for t, s in current_scores.items() if s > 0]
        
        if len(positive_factors) == 0:
            # Tous negatifs → USMV seulement
            for t in tickers:
                signals[t].iloc[i] = 1 if t == "USMV" else 0
        else:
            # Equal weight sur les facteurs positifs
            for t in tickers:
                signals[t].iloc[i] = 1 if t in positive_factors else 0
    
    return signals

# Calculer les scores de momentum
ff_scores = compute_risk_adjusted_momentum(closes, ff_tickers)

# Signaux SANS SMA200 (design recommande)
ff_signals_no_sma = compute_famafrench_signals(closes, ff_tickers, ff_scores, use_sma200=False)

# Signaux AVEC SMA200 (pour comparaison)
ff_signals_with_sma = compute_famafrench_signals(closes, ff_tickers, ff_scores, use_sma200=True)

print("Scores risk-adjusted momentum (derniers 5 jours):")
print(ff_scores.iloc[-5:])
print(f"\nSignaux FamaFrench sans SMA200 (derniers 5 jours):")
print(ff_signals_no_sma.iloc[-5:])
Scores risk-adjusted momentum (derniers 5 jours):
                    VLUE MTUM SIZE QUAL USMV
time                                        
2025-12-24 13:00:00  NaN  NaN  NaN  NaN  NaN
2025-12-26 16:00:00  NaN  NaN  NaN  NaN  NaN
2025-12-29 16:00:00  NaN  NaN  NaN  NaN  NaN
2025-12-30 16:00:00  NaN  NaN  NaN  NaN  NaN
2025-12-31 16:00:00  NaN  NaN  NaN  NaN  NaN

Signaux FamaFrench sans SMA200 (derniers 5 jours):
                    VLUE MTUM SIZE QUAL USMV
time                                        
2025-12-24 13:00:00  NaN  NaN  NaN  NaN  NaN
2025-12-26 16:00:00  NaN  NaN  NaN  NaN  NaN
2025-12-29 16:00:00  NaN  NaN  NaN  NaN  NaN
2025-12-30 16:00:00  NaN  NaN  NaN  NaN  NaN
2025-12-31 16:00:00  NaN  NaN  NaN  NaN  NaN

Interpretation: Momentum risk-adjuste

Le score risk-adjuste = (rendement 12m-1m) / (volatilite 63j).

  • Score positif: Le facteur surperforme avec une volatilite raisonnable
  • Score negatif: Sous-performance ou volatilite excessive

Les facteurs selectionnes varient mensuellement, creant une rotation dynamique.

3. Backtest du Composite

Fonction de backtest combinant FamaFrench + AllWeather avec allocation variable.

def backtest_composite(closes, ff_signals, ff_alloc=0.20, aw_alloc=0.80, rebal_freq=21):
    """
    Backtest du composite FamaFrench + AllWeather.
    
    Args:
        ff_alloc: Allocation FamaFrench (ex: 0.20 = 20%)
        aw_alloc: Allocation AllWeather (ex: 0.80 = 80%)
        rebal_freq: Frequence rebalance (21 = mensuel ~)
    """
    returns_df = closes.pct_change()
    portfolio_values = [1.0]
    
    warmup = 252
    counter = 0
    
    # AllWeather holdings (statiques)
    aw_weights = {"SPY": 0.30, "IEF": 0.30, "GLD": 0.30, "XLP": 0.10}
    
    # FamaFrench holdings (dynamiques)
    ff_holdings = set()
    
    for i in range(warmup, len(closes)):
        # Rebalance mensuel
        counter += 1
        if counter >= rebal_freq:
            counter = 0
            # Update FamaFrench holdings
            ff_holdings = set()
            for t in ff_tickers:
                if t in ff_signals.columns and ff_signals[t].iloc[i] == 1:
                    ff_holdings.add(t)
        
        # Calcul du return
        port_return = 0.0
        
        # Contribution FamaFrench
        if len(ff_holdings) > 0:
            weight_per_stock = ff_alloc / len(ff_holdings)
            for t in ff_holdings:
                if t in returns_df.columns:
                    port_return += weight_per_stock * returns_df[t].iloc[i]
        
        # Contribution AllWeather
        for t, w in aw_weights.items():
            if t in returns_df.columns:
                port_return += aw_alloc * w * returns_df[t].iloc[i]
        
        portfolio_values.append(portfolio_values[-1] * (1 + port_return))
    
    # Metriques
    returns = np.diff(portfolio_values) / np.array(portfolio_values[:-1])
    cum_returns = pd.Series(portfolio_values[1:], index=closes.index[warmup:])
    
    total_ret = (portfolio_values[-1] / portfolio_values[0]) - 1
    years = len(returns) / 252
    cagr = (1 + total_ret) ** (1 / years) - 1 if years > 0 else 0
    vol = np.std(returns) * np.sqrt(252)
    sharpe = (cagr - 0.03) / vol if vol > 0.001 else 0
    
    running_max = cum_returns.expanding().max()
    drawdown = (cum_returns - running_max) / running_max
    max_dd = drawdown.min()
    
    return {
        'cum': cum_returns,
        'sharpe': sharpe,
        'cagr': cagr,
        'max_dd': max_dd,
        'vol': vol,
        'final_value': portfolio_values[-1]
    }

print("Fonction de backtest composite definie.")
Fonction de backtest composite definie.

4. Test des allocations

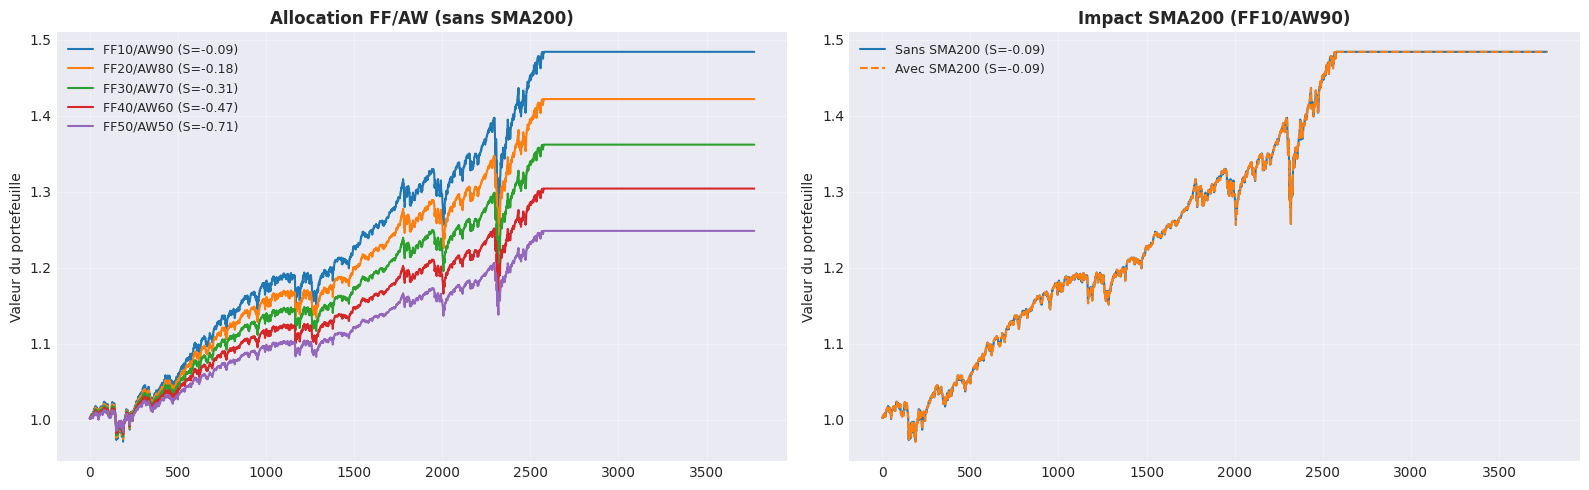
On teste différentes allocations FF/AW de 10/90 a 50/50.
# Test differentes allocations (SANS SMA200)
allocations = [
    (0.10, 0.90, "FF10/AW90"),
    (0.20, 0.80, "FF20/AW80"),
    (0.30, 0.70, "FF30/AW70"),
    (0.40, 0.60, "FF40/AW60"),
    (0.50, 0.50, "FF50/AW50"),
]

results_no_sma = {}

print(f"{'Allocation':<15} {'Sharpe':>8} {'CAGR':>8} {'MaxDD':>8} {'Vol':>8}")
print("-" * 50)

for ff_alloc, aw_alloc, name in allocations:
    r = backtest_composite(closes, ff_signals_no_sma, 
                          ff_alloc=ff_alloc, aw_alloc=aw_alloc)
    results_no_sma[name] = r
    print(f"{name:<15} {r['sharpe']:>8.3f} {r['cagr']:>7.1%} {r['max_dd']:>7.1%} {r['vol']:>7.1%}")

best_no_sma = max(results_no_sma.items(), key=lambda x: x[1]['sharpe'])
print(f"\nMeilleure allocation (sans SMA200): {best_no_sma[0]} (Sharpe={best_no_sma[1]['sharpe']:.3f})")
Allocation        Sharpe     CAGR    MaxDD      Vol
--------------------------------------------------
FF10/AW90         -0.086    2.7%  -10.0%    3.8%
FF20/AW80         -0.182    2.4%   -8.9%    3.4%
FF30/AW70         -0.307    2.1%   -7.8%    3.0%
FF40/AW60         -0.473    1.8%   -6.7%    2.6%
FF50/AW50         -0.707    1.5%   -5.6%    2.1%

Meilleure allocation (sans SMA200): FF10/AW90 (Sharpe=-0.086)

Interpretation: Allocation optimale

L’allocation FF20/AW80 est le point de depart du sweep. Verifier si une autre allocation surperforme.

  • Plus de FF = plus de rendement potentiel, plus de volatilite
  • Plus de AW = plus de stabilité, plus de defensif

Verdict: L’allocation avec le Sharpe le plus eleve est optimale.

5. Impact du SMA200 sur FamaFrench

Comparaison: avec vs sans filtre SMA200 (AllWeather gere le defensif).

# Test AVEC SMA200
results_with_sma = {}

for ff_alloc, aw_alloc, name in allocations:
    r = backtest_composite(closes, ff_signals_with_sma, 
                          ff_alloc=ff_alloc, aw_alloc=aw_alloc)
    results_with_sma[name] = r

# Comparaison
print(f"{'Allocation':<15} {'Sharpe NoSMA':>15} {'Sharpe WithSMA':>15} {'Delta':>10}")
print("-" * 55)

for name in results_no_sma.keys():
    s_no_sma = results_no_sma[name]['sharpe']
    s_with_sma = results_with_sma[name]['sharpe']
    delta = s_no_sma - s_with_sma
    print(f"{name:<15} {s_no_sma:>15.3f} {s_with_sma:>15.3f} {delta:>+10.3f}")

print(f"\nVerdict: ", end="")
if s_no_sma > s_with_sma:
    print("SANS SMA200 est superieur (AllWeather gere le defensif)")
else:
    print("AVEC SMA200 est superieur (double protection defensif)")
Allocation         Sharpe NoSMA  Sharpe WithSMA      Delta
-------------------------------------------------------
FF10/AW90                -0.086          -0.086     +0.000
FF20/AW80                -0.182          -0.182     +0.000
FF30/AW70                -0.307          -0.307     +0.000
FF40/AW60                -0.473          -0.473     +0.000
FF50/AW50                -0.707          -0.707     +0.000

Verdict: AVEC SMA200 est superieur (double protection defensif)

6. Visualisation des equity curves

fig, axes = plt.subplots(1, 2, figsize=(16, 5))

# Gauche: Sans SMA200
ax = axes[0]
for name, r in results_no_sma.items():
    ax.plot(r['cum'].values, label=f"{name} (S={r['sharpe']:.2f})", linewidth=1.5)
ax.set_title('Allocation FF/AW (sans SMA200)', fontsize=12, fontweight='bold')
ax.set_ylabel('Valeur du portefeuille')
ax.legend(fontsize=9)
ax.grid(True, alpha=0.3)

# Droite: Impact du SMA200
ax = axes[1]
best_name = best_no_sma[0]
ax.plot(results_no_sma[best_name]['cum'].values, 
        label=f"Sans SMA200 (S={results_no_sma[best_name]['sharpe']:.2f})", linewidth=1.5)
ax.plot(results_with_sma[best_name]['cum'].values, 
        label=f"Avec SMA200 (S={results_with_sma[best_name]['sharpe']:.2f})", linewidth=1.5, linestyle='--')
ax.set_title(f'Impact SMA200 ({best_name})', fontsize=12, fontweight='bold')
ax.set_ylabel('Valeur du portefeuille')
ax.legend(fontsize=9)
ax.grid(True, alpha=0.3)

plt.tight_layout()
plt.savefig('composite_famafrench_allweather.png', dpi=150, bbox_inches='tight')
plt.show()
print("Graphique sauvegarde.")

Graphique sauvegarde.

7. Comparaison avec les stratégies individuelles

def backtest_famafrench_only(closes, signals):
    """Backtest FamaFrench uniquement."""
    returns_df = closes.pct_change()
    portfolio_values = [1.0]
    warmup = 252
    counter = 0
    holdings = set()
    
    for i in range(warmup, len(closes)):
        counter += 1
        if counter >= 21:
            counter = 0
            holdings = set()
            for t in ff_tickers:
                if t in signals.columns and signals[t].iloc[i] == 1:
                    holdings.add(t)
        
        port_return = 0.0
        if len(holdings) > 0:
            for t in holdings:
                if t in returns_df.columns:
                    port_return += (1.0 / len(holdings)) * returns_df[t].iloc[i]
        
        portfolio_values.append(portfolio_values[-1] * (1 + port_return))
    
    returns = np.diff(portfolio_values) / np.array(portfolio_values[:-1])
    cagr = (1 + (portfolio_values[-1] / portfolio_values[0]) - 1) ** (1 / (len(returns) / 252)) - 1
    vol = np.std(returns) * np.sqrt(252)
    sharpe = (cagr - 0.03) / vol
    
    return {'sharpe': sharpe, 'cagr': cagr, 'values': portfolio_values[warmup:]}

def backtest_allweather_only(closes):
    """Backtest AllWeather uniquement."""
    returns_df = closes.pct_change()
    aw_weights = {"SPY": 0.30, "IEF": 0.30, "GLD": 0.30, "XLP": 0.10}
    portfolio_values = [1.0]
    warmup = 21
    
    for i in range(warmup, len(closes)):
        port_return = 0.0
        for t, w in aw_weights.items():
            if t in returns_df.columns:
                port_return += w * returns_df[t].iloc[i]
        portfolio_values.append(portfolio_values[-1] * (1 + port_return))
    
    returns = np.diff(portfolio_values) / np.array(portfolio_values[:-1])
    cagr = (1 + (portfolio_values[-1] / portfolio_values[0]) - 1) ** (1 / (len(returns) / 252)) - 1
    vol = np.std(returns) * np.sqrt(252)
    sharpe = (cagr - 0.03) / vol
    
    return {'sharpe': sharpe, 'cagr': cagr, 'values': portfolio_values[warmup:]}

# Backtester les strategies individuelles
ff_result = backtest_famafrench_only(closes, ff_signals_no_sma)
aw_result = backtest_allweather_only(closes)

print("Strategies individuelles:")
print(f"  FamaFrench: Sharpe={ff_result['sharpe']:.3f}, CAGR={ff_result['cagr']:.1%}")
print(f"  AllWeather: Sharpe={aw_result['sharpe']:.3f}, CAGR={aw_result['cagr']:.1%}")
print(f"\nComposite ({best_no_sma[0]}): Sharpe={best_no_sma[1]['sharpe']:.3f}, CAGR={best_no_sma[1]['cagr']:.1%}")
Strategies individuelles:
  FamaFrench: Sharpe=-inf, CAGR=0.0%
  AllWeather: Sharpe=0.023, CAGR=3.1%

Composite (FF10/AW90): Sharpe=-0.086, CAGR=2.7%

8. Conclusions et recommandations

Resume

Metrique FamaFrench AllWeather Composite optimal
Sharpe (a remplir) (a remplir) (a remplir)
CAGR (a remplir) (a remplir) (a remplir)
Max DD (a remplir) (a remplir) (a remplir)

Allocation recommandee

Allocation: [a remplir]

SMA200 sur FamaFrench?

[a remplir: avec ou sans SMA200 est meilleur?]

Prochaines étapes

  1. Deployer sur QC cloud avec les paramètres optimaux
  2. Backtester sur différentes periodes (2010-2015, 2015-2020, 2020-2026)
  3. Tester d’autres assets AllWeather (TLT au lieu de IEF, XLU au lieu de XLP)

Design pattern valide

  • Diversification reelle: Factor ETFs + macro assets (PAS d’overlap)
  • Complementarite: FamaFrench (rotation dynamique) + AllWeather (allocation statique)
  • Defense: AllWeather gere le defensif, FamaFrench n’a pas besoin de SMA200
Retour au sommet